Digital complexity signals a new phase for 3PL users
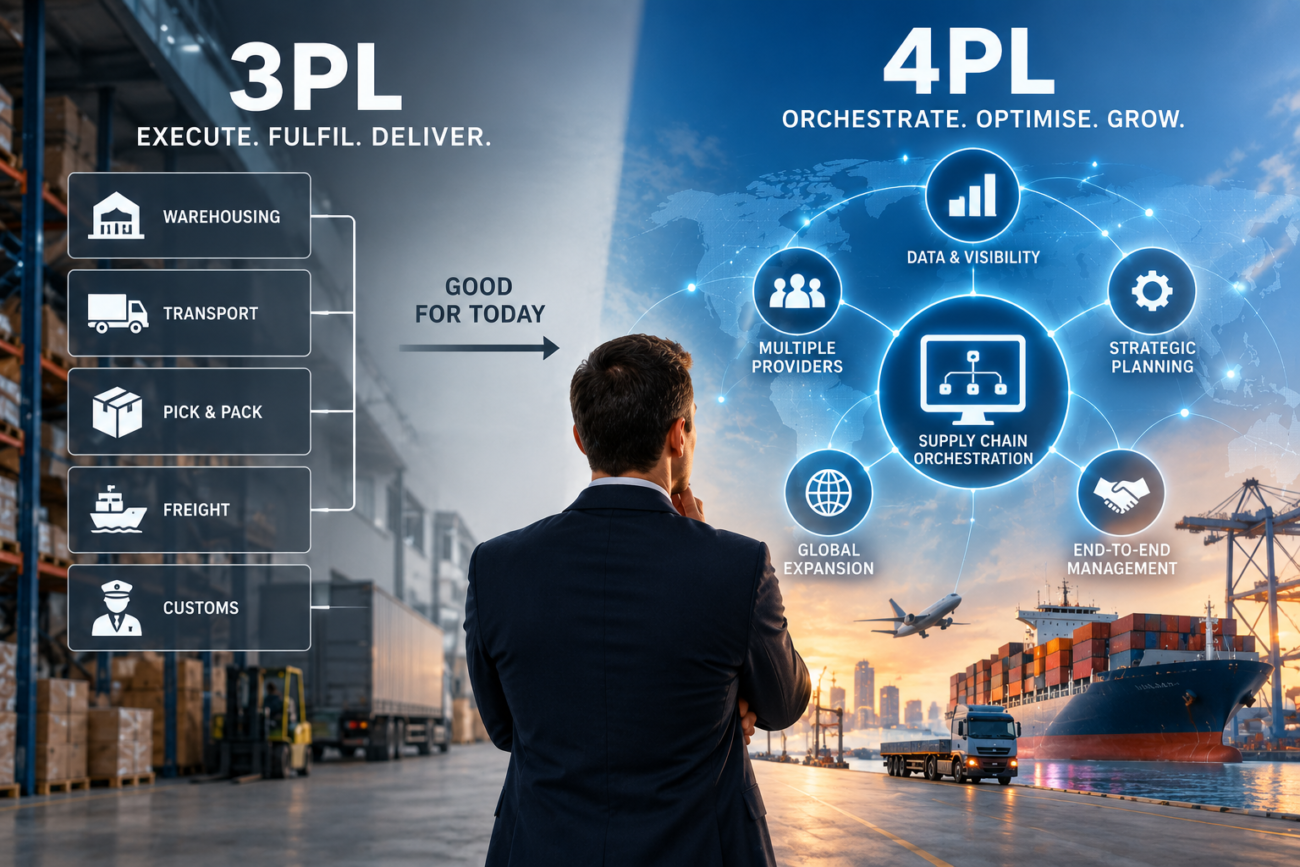
Industrial growth changes the demands placed on logistics. A 3PL that performs well for a company in one market may struggle to provide consistent visibility once the business adds countries, carriers, warehouses and regional partners. The resulting issue is often architectural: the network has become too fragmented to manage through separate provider relationships.
Paul Lockwood, UK and Ireland Group Managing Director at SEKO Logistics, highlights four symptoms. The first is weak technology alignment. Multiple logistics providers can bring separate warehouse management systems, transport management systems and EDI connections. Inventory and order information then has to be reconciled across environments, making automation and exception handling harder to scale.
The technology gap is reflected in the 2026 30th Annual Third-Party Logistics Study. While 90% of shippers consider technology capability critical when selecting a 3PL, only 57% report satisfaction with their provider’s technology. For industrial operations, poor integration can weaken planning accuracy and slow responses to disruption.
From provider management to network orchestration
A second signal is that the provider’s geographic footprint no longer matches the company’s growth. The study says 50% of shippers and 62% of 3PLs are seeing efforts to consolidate provider numbers. Consolidation can reduce interfaces, but it also points to a need for consistent governance across the remaining network.
The third shift is strategic. Logistics decisions increasingly involve inventory positioning, landed cost, resilience and market entry, not only fulfilment. When several partners contribute to one flow, the business may need a control layer that can compare performance and coordinate action across the network.
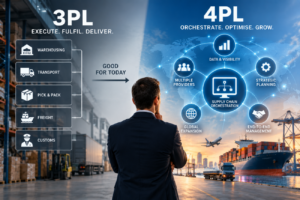
A fourth-party logistics model can provide that orchestration. It does not necessarily replace existing 3PLs; instead, it can coordinate multiple providers and systems. This may support standardised data, common performance measures and more structured responses to supply chain disruption.
Technology does not remove the need for judgement
Adopting 4PL still involves trade-offs. The transition can be complex, direct control may be reduced and the cost structure will change. Companies operating in only one or two markets may achieve more by improving their current 3PL relationship.
The practical decision is therefore not whether 4PL is inherently more advanced. It is whether the company can still manage its logistics through isolated provider contracts without sacrificing visibility, resilience and operational control.